

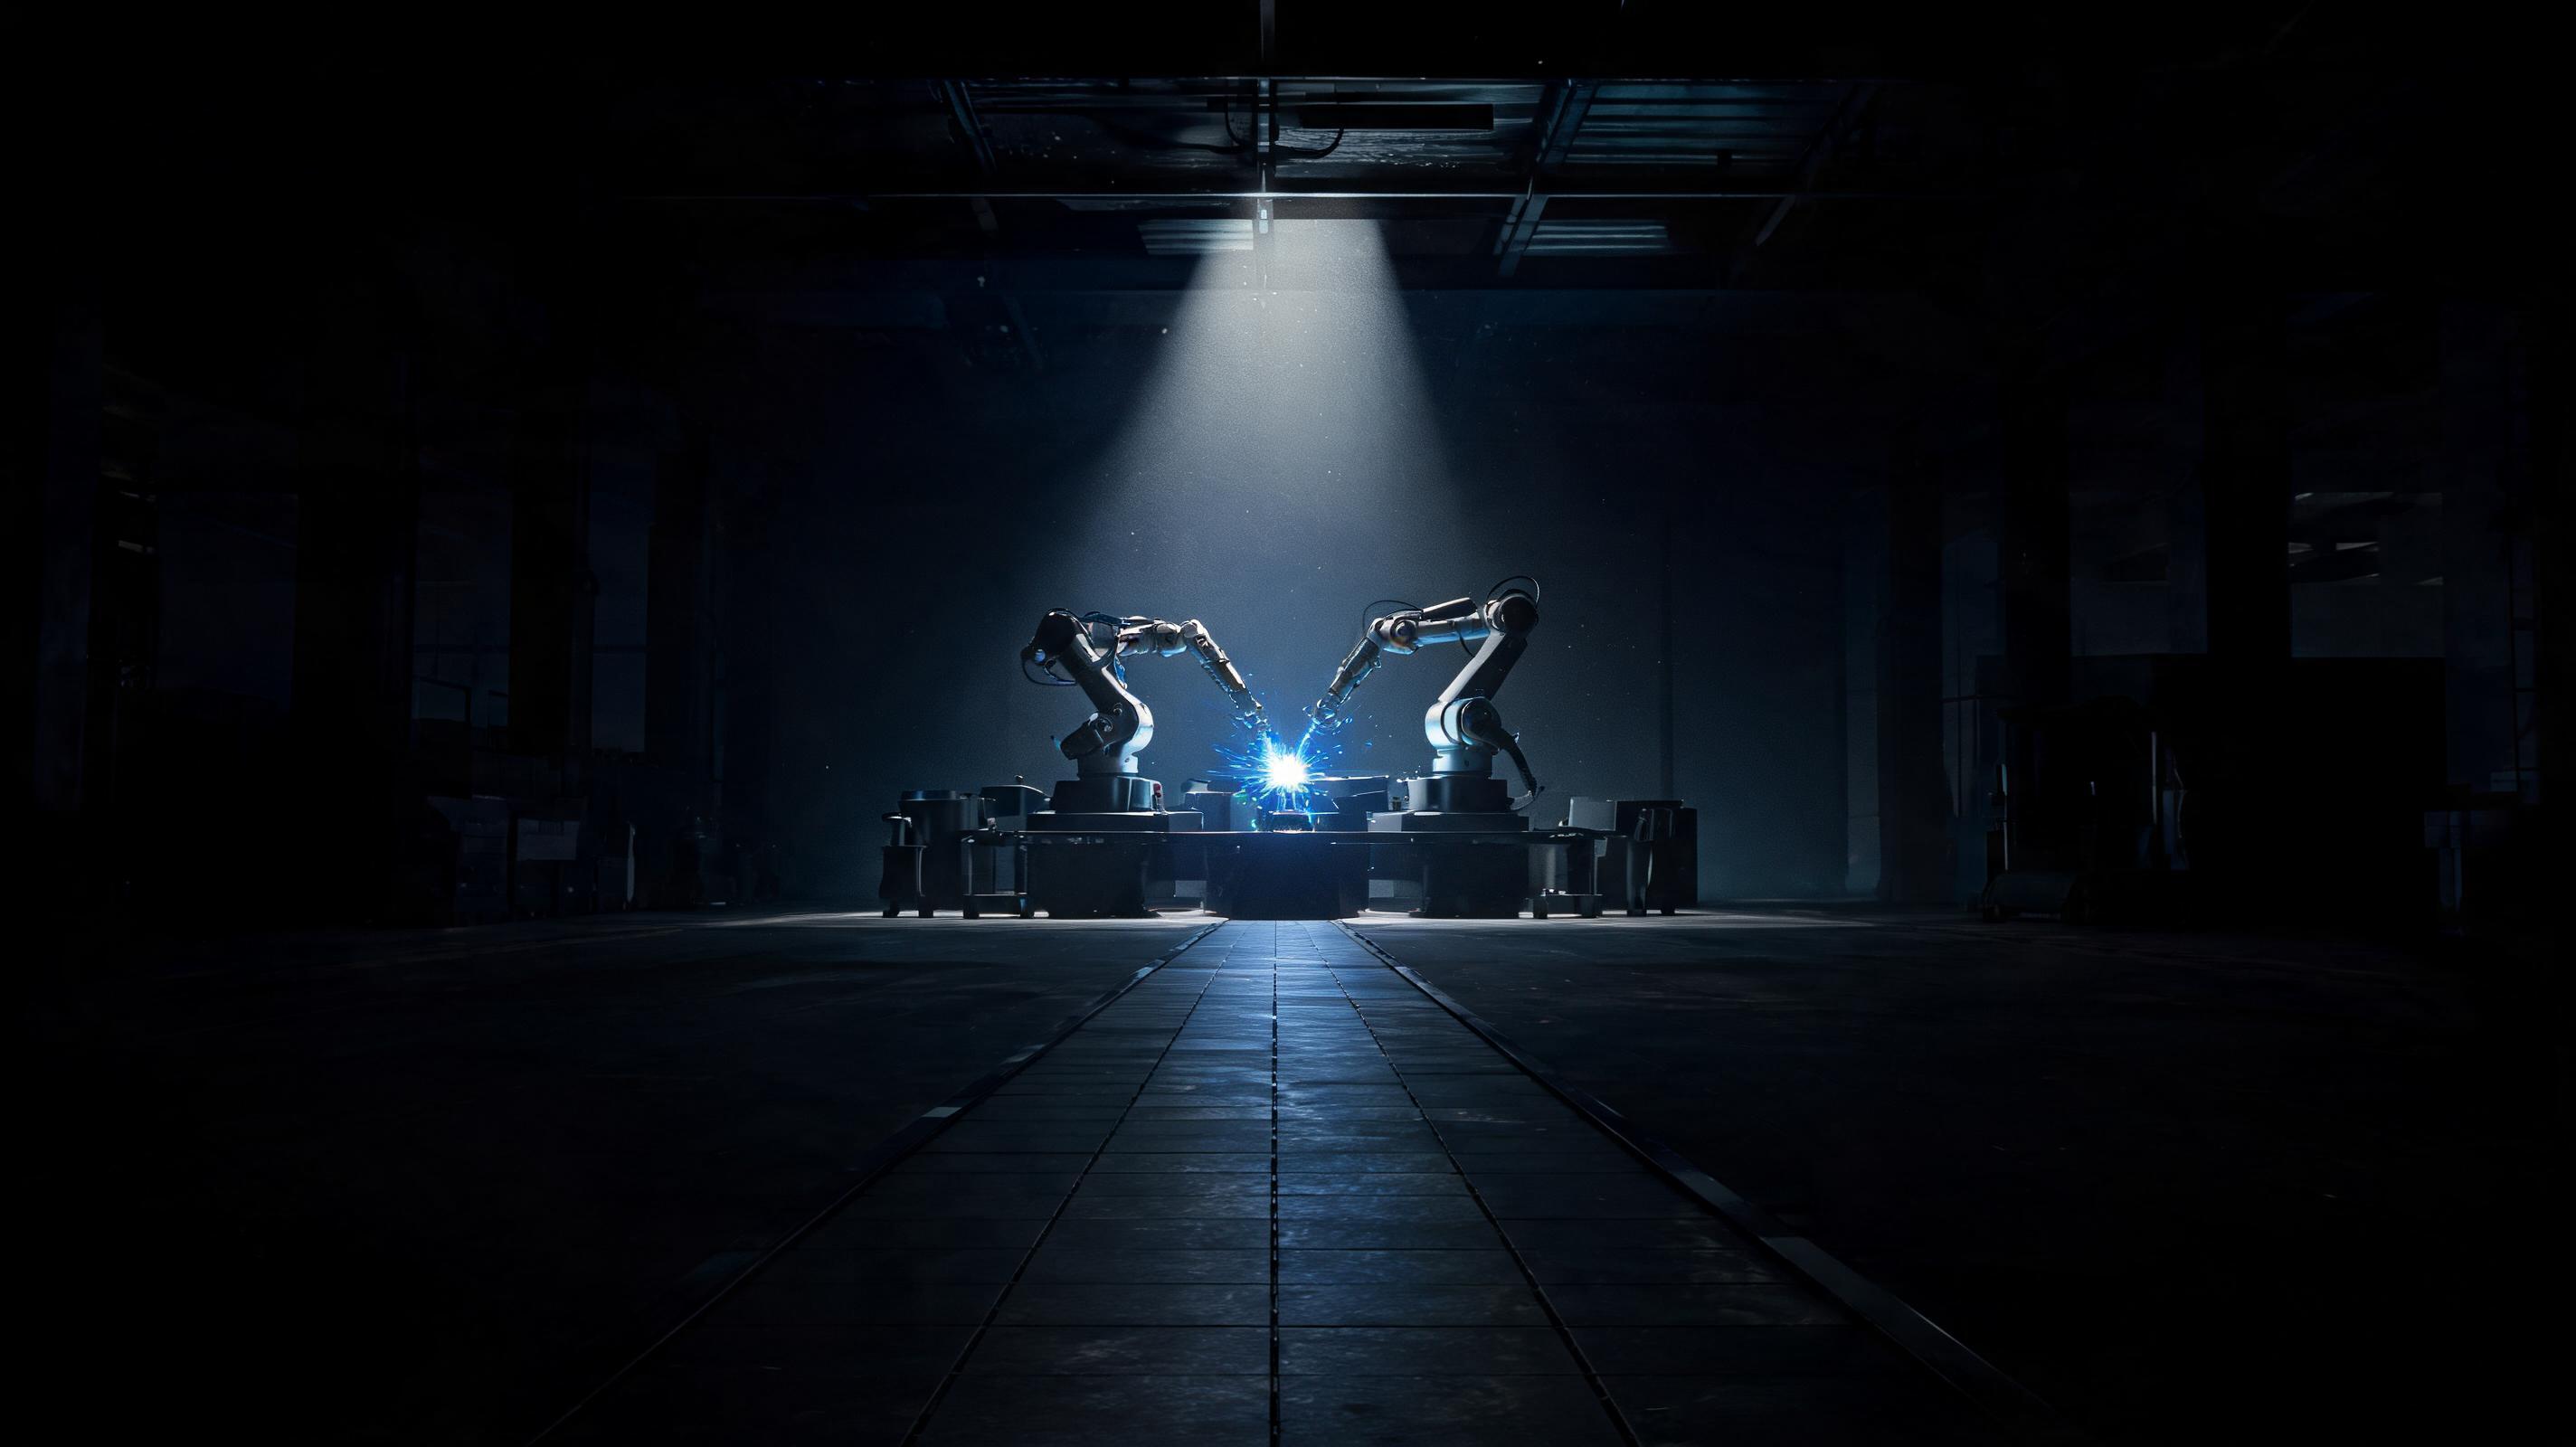
Qianzhan Industry Research Institute, one of China's best-known industrial research houses, has released the latest edition of its flagship study, the "2026-2031 Global and China Welding Robot Industry Development Prospect and Investment Strategy Planning Analysis Report." The report positions itself as a strategic planning reference for manufacturers, integrators, and investors entering or scaling in the welding automation sector, and it arrives at a moment when China's welding robot market is shifting from imported, rule-based automation toward domestically developed, data-driven intelligent welding.
Scope and structure
The study is organized as a full industry chain analysis. It opens with a definitional chapter covering how welding robots are classified, which regulatory bodies and standards regimes govern the sector, and how the industry chain is structured from core components to system integration. It then surveys the global market — production, installations, sales volumes, competitive concentration, and regional development in Japan, the United States, South Korea, and Germany — before turning to a detailed assessment of China's market: supply and demand, imports and exports under the relevant HS codes, public procurement and tendering activity, and pricing levels.
Technology roadmap and hot tracks
A dedicated technology chapter maps the welding robot technology landscape end to end: robot body design, welding power source technology, sensing and adaptive control of the weld process, multi-robot collaboration for welding workstations and production lines, seam tracking and path planning, remote operation for extreme environments, offline programming and simulation, and systems integration. It also examines newer intersections such as machine vision plus welding robots and artificial intelligence plus welding robots, which the report identifies as the key research directions going forward.
The investment analysis section tracks funding sources, market financing dynamics, IPO activity, cross-sector investment, and merger-and-restructuring trends in the sector. Company case studies profile leading Chinese players including Hangzhou Kaierda Welding Robots, SIASUN Robot and Automation, Jiefu Equipment (Wuhan), Nanjing Estun Automation, and Chengdu KANOP Robotics, alongside the global incumbents ABB, KUKA, FANUC, and Yaskawa.
Components and applications
The report also breaks down the upstream component market — reducers, servo motors, and controllers — and the welding system layer, including wire-feeding systems, specialized torches, welding power sources, seam-tracking sensors, positioners, fixtures, and arc-welding software packages. On the demand side, it analyzes segment markets for arc welding, spot welding, brazing, and laser welding robots, and maps applications across automotive manufacturing, construction machinery, electronics and electrical equipment, shipbuilding, and battery manufacturing.
Outlook
Looking forward, the report forecasts the industry's five-year prospects, evaluates growth potential and exit barriers, and closes with investment risk warnings and opportunity analysis across the value chain — from weak links in the supply chain to regional market opportunities. For a sector now contending with a shrinking pool of skilled human welders, the study's central message is that welding robots are moving decisively into a scale-up phase, with domestic substitution, intelligent welding, and overseas expansion as the defining competitive themes through 2031.